Future Value Annuity Calculator
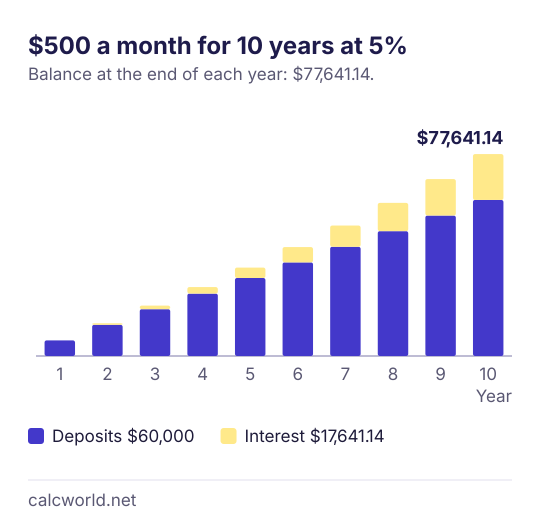
The future value annuity calculator shows what a series of equal payments grows to with compound interest. $500 a month for 10 years at 5% a year, compounded monthly, grows to $77,641.14.
Sources: Wikipedia, Investor.gov Updated
Calculate the future value of regular payments with compound interest. Enter your payment amount, interest rate, time period, and frequencies below.
Example: $500 a month for 10 years at 5%
If you invest $500 monthly at 5% annual interest for 10 years with monthly compounding:
- Future Value: $77,641.14
- Total Contributions: $60,000.00
- Interest Earned: $17,641.14
What the future value of an annuity means
An annuity here is a series of equal payments at regular intervals, such as $500 every month. Its future value is what all the payments plus the interest they earn add up to at the end.
Each payment compounds for a different length of time: the first monthly deposit earns interest for almost the whole term and the last one for almost none. That makes it different from a single lump sum.
How to calculate the future value of an annuity
For an ordinary annuity, with payments at the end of each period, FV = P × ((1 + i)ⁿ − 1) ÷ i, where P is the payment, i the rate per period and n the number of payments.
- Find the rate per payment period: 5% ÷ 12 = 0.4167% a month.
- Count the payments: 10 years × 12 = 120.
- Apply the formula: 500 × ((1.004167)¹²⁰ − 1) ÷ 0.004167 = 500 × 155.28 = $77,641.14.
The payments total 500 × 120 = $60,000, so $17,641.14 is interest. The power in step 3 is what the exponent calculator works out, and the formula itself is the sum of a geometric sequence with ratio 1 + i.
When payments and compounding happen at different times
Payment frequency and compounding frequency can be set separately, for example monthly deposits into an account that compounds quarterly. The calculator then turns the yearly rate into an effective annual rate for the compounding, and that into a rate per payment period.
In the example both are monthly, so the effective annual rate is (1 + 0.05 ÷ 12)¹² − 1 = 5.116% and the rate per payment is back to 5% ÷ 12.
Ordinary annuity or annuity due
"End of period" is an ordinary annuity: each deposit arrives after that period's interest. "Beginning of period" is an annuity due: the deposit comes first and earns interest for that period too.
The calculator handles an annuity due by multiplying the ordinary result by 1 + i. For the example that is $77,641.14 × 1.004167 = $77,964.64, a gap that grows with more payments and higher rates.
Limits of the projection
The rate is held fixed for the whole term, and taxes, fees and inflation are left out. The SEC's compound interest calculator is another way to check regular savings.
To see how a single value grows at a steady rate, use the percent growth calculator; for a home's value, the home appreciation calculator. All the money tools are on the finance calculators page.
Future Value Annuity Calculator: FAQ
What is the difference between an ordinary annuity and an annuity due?
In an ordinary annuity each payment comes at the end of the period; in an annuity due it comes at the start, so every payment earns one more period of interest. The example grows to $77,641.14 as an ordinary annuity and $77,964.64 as an annuity due.
How much of the future value is interest?
Subtract what you paid in. 120 payments of $500 are $60,000, so $17,641.14 of the $77,641.14 is interest.
What if I also start with a lump sum?
Grow the lump sum separately at compound interest and add it. The investment calculator in financial calculators does both together.
Sources
- Wikipedia: Annuity — annuity-immediate and annuity-due, and the future value of a level annuity (checked October 16, 2026)
- Investor.gov (US SEC): Compound Interest Calculator — regular contributions growing with compound interest (checked October 16, 2026)